The project, in numbers
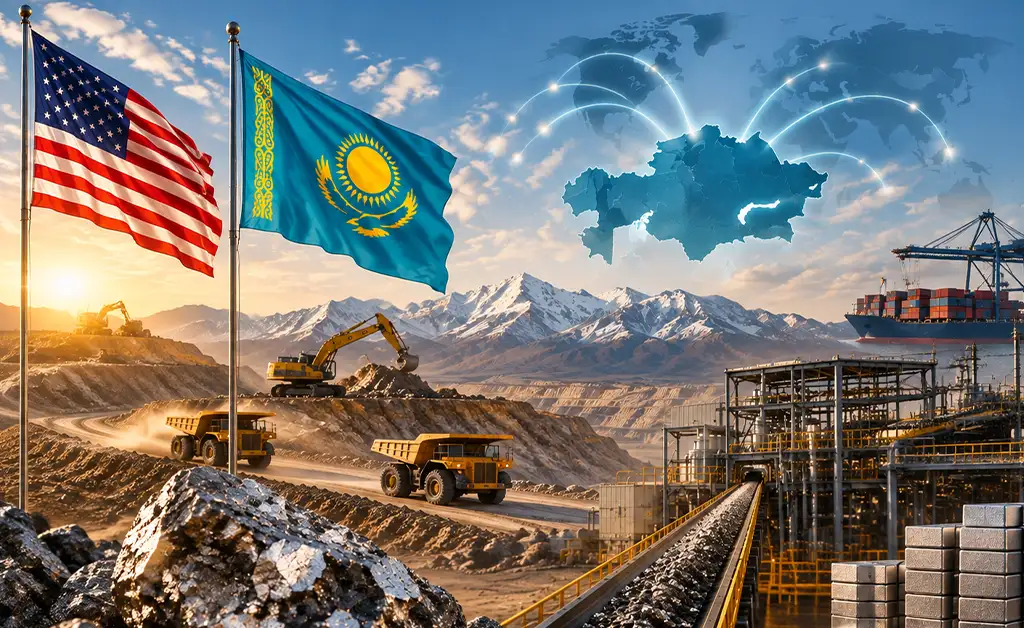
For the first time, the financial and structural detail of America’s tungsten play in Kazakhstan has been published in one place. Cove Capital holds 70 per cent and the state holding company Tau-Ken Samruk holds 30 per cent of a $1.1 billion project developing the Severny Katpar and Verkhneye Kairakty deposits in the Karaganda region.
The target is roughly 5,000 tonnes of tungsten trioxide annually. Mining is scheduled to begin in 2030. Critically, processing will be carried out inside Kazakhstan rather than exported as raw concentrate.
Each of those four elements — the ownership split, the volume, the timeline and the domestic processing commitment — tells a different part of the story, and each carries a different implication for American industrial buyers.
Why tungsten, and why now
Tungsten sits in an awkward position within the critical minerals conversation. It attracts less attention than rare earths or lithium, but it is functionally irreplaceable in cutting tools, armour penetrators, drilling equipment and high-temperature alloys. There is no substitute of comparable hardness at comparable cost.
It is also among the most concentrated supply chains in the industrial economy, with Chinese producers holding a dominant share of both mining and, more importantly, processing. A Western mine that ships concentrate to Chinese refineries has not diversified anything. That is why the domestic processing element of the Kazakh project is the detail worth dwelling on.
The 70/30 structure
The ownership split is unusual for a Central Asian resource project of this scale. Majority foreign control with a minority state holding through Tau-Ken Samruk gives the commercial partner operational latitude while keeping the sovereign wealth vehicle aligned with the project’s success.
For potential offtake partners, that structure reduces a familiar category of risk. Projects where the state holds a controlling stake are more exposed to shifts in domestic political priority; projects with no state participation at all are more exposed to permitting friction and local resistance. A 30 per cent sovereign stake is, in practice, a stabilising instrument.
It also signals something about Astana’s calculation. Kazakhstan has chosen to take value capture through processing and equity rather than through resource nationalism — a materially different model from the one that has frustrated Western investors elsewhere in the region.
The 2030 window
First production in 2030 means the project changes nothing about current-year supply. American defence primes, machine tool manufacturers and drilling equipment suppliers will source tungsten in 2027, 2028 and 2029 largely as they do today.
What the timeline does create is a procurement planning window. Offtake agreements for projects of this type are typically negotiated three to five years ahead of first production, because the financing depends on them. That places the practical decision point for American buyers somewhere between now and 2028.
Firms that wait until 2030 to think about non-Chinese tungsten will be negotiating for residual volumes at spot-linked pricing. Firms that engage during the financing phase will be negotiating as counterparties whose commitment the project needs.
The regional pattern
The Kazakh tungsten project is not isolated. In Tajikistan, the Anzob facility operated by Comsup Commodities produces around 22,000 tonnes of antimony a year — approximately one-fifth of estimated global output in 2025. Uzbekistan has announced a portfolio of 120 technological metals projects worth $4.2 billion for the 2026 to 2030 period.
Taken together, these represent the first time American-linked critical minerals activity in Central Asia can be described at the level of named projects, identified operators and specific tonnages rather than as memoranda of understanding. That is a meaningful change in the maturity of the story.
It also arrived in the same week as a Congressional hearing on Kazakh critical minerals — a coincidence of timing that raises the political salience of both.
What to watch
The markers that will indicate whether this project is on track: confirmation of the debt financing package, which for a $1.1 billion capital programme will require either development finance participation or a substantial offtake-backed structure; announcements of processing technology partners, since the domestic refining commitment requires capability Kazakhstan does not currently hold at scale; and the first named offtake agreements, which will reveal whether American or European buyers move first.
For American defence and machine tool suppliers, the immediate task is unglamorous: establish whether tungsten appears in your bill of materials at all, and where in the tier structure it enters. A surprising number of firms discover the exposure only when the price moves.
