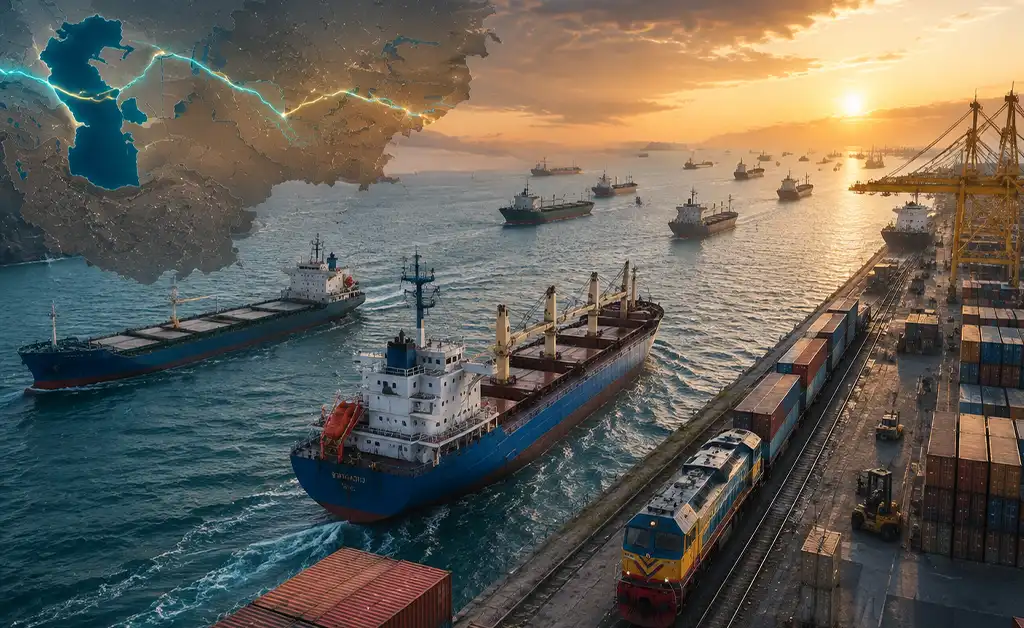
The ambition to move 10 million tonnes of cargo through the Middle Corridor by 2027 is a powerful vision, but the current reality of the Caspian fleet paints a more nuanced picture. While regional governments are making significant strides in modernizing rail lines and terminals, the actual maritime capacity remains a significant bottleneck. The disparity between cargo volume growth and the number of available vessels is becoming increasingly apparent to international logistics players.
This Caspian cargo fleet bottleneck is a structural issue that will require sustained investment over the coming years. Since 2013, the introduction of new vessels has failed to keep pace with the exponential growth in demand, leaving the route vulnerable to delays during peak shipping seasons. For regional operators like KTZ and ASCO, the challenge is clear: modernize the fleet, improve the efficiency of port operations, and expand the number of active vessels to meet the ambitious transit goals set for the end of the decade.
The potential for investors in this space is substantial. Developing a modern fleet of specialized vessels represents a clear Middle Corridor investment opportunity for those who have the capital and the expertise to navigate the regional requirements. Whether through direct investment in shipping companies or the development of automated terminal technology, there are numerous ways to participate in this necessary expansion. As the route matures, the reliability of transit will become the primary differentiator for shippers who are deciding whether to route their goods through the Caspian.
To reach the 10 million tonne goal, planners must also focus on the digital side of logistics. Enhancing the visibility of cargo as it moves across the water is just as important as having enough ships. Digital platforms that track fleet movement and predict transit times are essential for convincing international corporations to commit to this route. Strengthening Trans Caspian route reliability shippers confidence in the system will rely on these technological improvements just as much as physical infrastructure.
Ultimately, the Middle Corridor is moving from a theoretical alternative to an operational necessity. While the current fleet shortage is a hurdle, it is also a sign of the corridor’s success in attracting global attention. As regional actors continue to address these capacity constraints, the route will become an increasingly stable pillar of global trade. Investors and logistics managers who recognize the scale of this opportunity now will be well positioned to benefit as the infrastructure catches up with the rapidly growing transit demand.
